 CGQI
Define a factor
Select a financial data input and use factor analysis to define the signal to investigate.
Product focus
Capital Quant integrates multidimensional financial data, AI factor analysis, historical strategy backtesting and quantitative model research. Users can construct, test and refine strategies around their own research questions.
A starting question for this workflow is How does a strategy behave on historical data?
Capabilities
Select a financial data input and use factor analysis to define the signal to investigate.
Build a strategy around the signal and test it against historical observations.
Compare results, revisit the assumptions and refine the quantitative model.
Illustrative workflow
A dated investment universe, financial observations with release times, rebalance dates and a cost assumption.
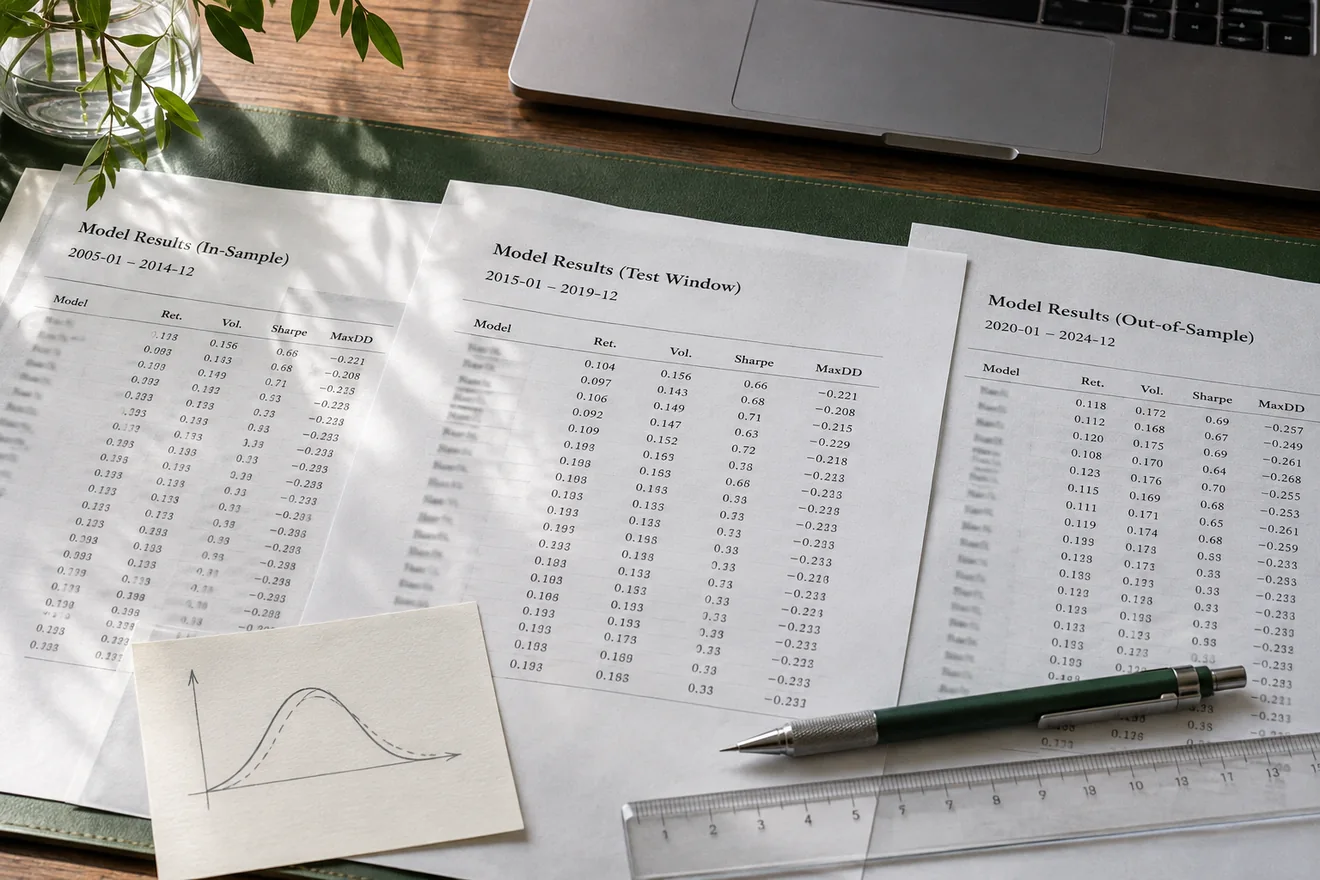
Rank the universe using only data available on each date. Set the rule in an earlier window and examine it in a later one.
An out-of-sample result with turnover, drawdown and a record of how the conclusion changes when costs rise.
A backtest can use the right formula and still have the wrong information. Start by rebuilding what a researcher could actually have known on each test date.